Looking for mortgage brokers in Wentworth Falls who understand Upper Mountains homes? We're a mortgage broker based in Glenbrook, about 35 minutes down the highway, and we compare 70+ lenders for Wentworth Falls owners and buyers. Maybe you own your home outright and want to borrow against it, want a better rate on the loan you've got, or are buying your first place where most houses now cost more than $1m. The lender pays us when your loan settles, so our advice costs you nothing.
A local broker will call you within 1 business hour. No fees, no obligation.
Nearly half of Wentworth Falls households have no mortgage at all. When they come to us, it's usually to borrow against a home they own, help their kids buy, or move to something that suits the next stage. We also help first home buyers and refinancers.
Own your home outright and want to renovate, help family or buy another property? We'll work out how much of your equity lenders will let you use, and what the repayments look like.
Lenders ask older borrowers how a loan will be repaid once work stops. We help you set out a plan they'll accept, using super, downsizing or other assets.
Most Wentworth Falls houses now sit above $1m, past the NSW first home buyer stamp duty concession. We'll show you the real cost and the schemes that still apply.
Whatever you’re trying to buy, build or restructure — there’s a lender on our panel for it.
Buying your first home? We'll walk you through the 5% deposit scheme, the stamp duty concessions and what your budget can realistically buy in the suburbs you're looking at.
Learn more →If you haven't checked your rate lately, you could be paying a "loyalty tax". We'll run a free health check across 70+ lenders and only recommend a switch if the numbers stack up.
Learn more →Buying an investment property, or your next one? We set up investment loans with tax, future borrowing power and long-term growth in mind, and work with your accountant on the structure.
Learn more →Building, or knocking down and rebuilding? Construction loans use progress payments and a valuation of the finished home. We work with your builder and lender so each payment is released on time.
Learn more →Self-employed, contracting or running a small business? We know how each lender looks at BAS statements, business income and accountant letters, and which ones are most likely to say yes.
Learn more →When the right place comes up, it doesn't sit on the market for long. Pre-approval means you can bid at auction or make a serious offer knowing roughly what a lender will approve.
Learn more →No jargon, no surprises. Just clear advice and a clear plan from your first call to well beyond settlement.
We’ll get to know your goals, your situation and what kind of loan you actually need. No commitment, no pressure.
We compare across 70+ lenders and come back with two or three real options, explained in plain English — rate, repayments, features and total cost.
We handle the paperwork, chase the lender, and keep you in the loop the whole way. You sign — we do the rest.
We don’t disappear once your loan settles. We review your rate annually and we’re always a phone call away if your situation changes.
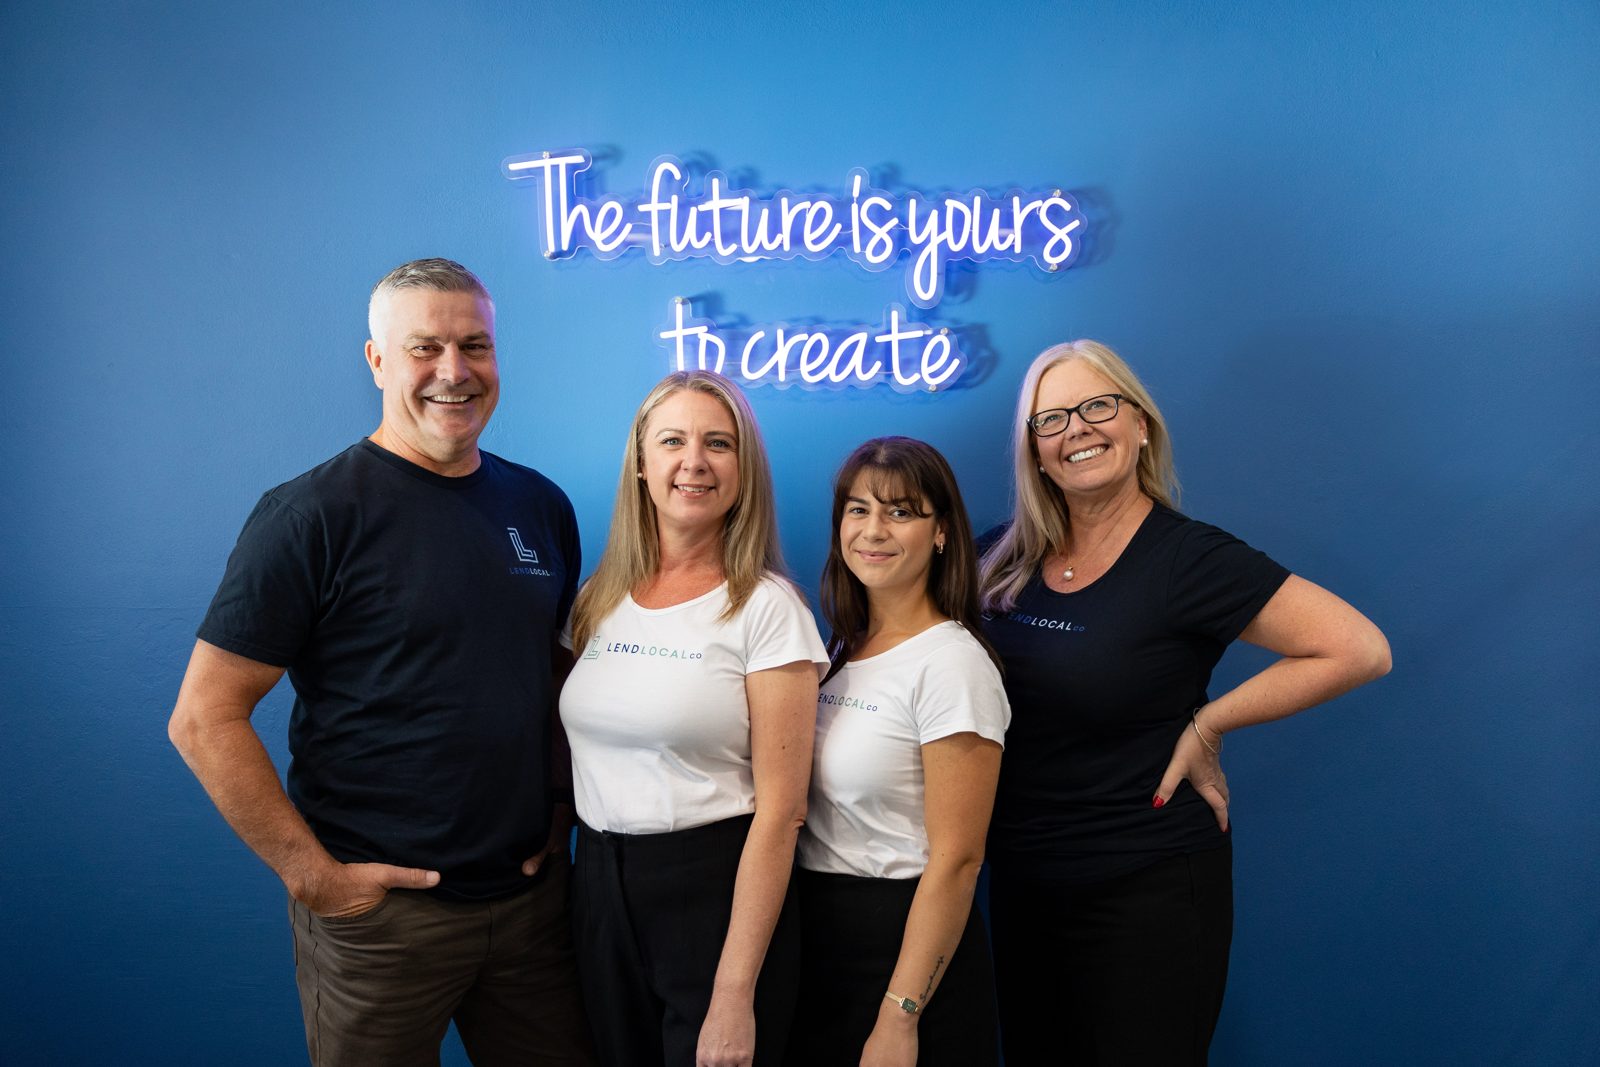
We’re not a call centre or a faceless online form. When you work with Lend Local Co, you get a small, tight-knit team of mortgage professionals who live and work in the same community you do.
From your very first call to the day your loan settles, you’ll deal with the same people — people who remember your name, understand your goals, and pick up the phone when you ring.
Free calculators and plain-English guides from our team. Use them to get a rough idea, then we'll check the real numbers across 70+ lenders.
See roughly how much a lender could let you borrow based on your income and expenses.
Estimate your weekly, fortnightly or monthly repayments at different rates and loan sizes.
See how much interest and time you could save by paying a little extra each month.
Worked examples for a unit and a house, the 5% Deposit Scheme and stamp duty.
What you can borrow, grants and schemes, and why pre-approval matters.
From a rate starting with 6 to an expiring fixed term, when a review pays off.
Full-doc, low-doc and alt-doc explained, and how to strengthen your application.
No. Our office is on Park Street in Glenbrook, about 35 minutes down the highway, and we also see clients at our Windsor office by appointment. Most Wentworth Falls clients do everything by phone and video, but you're welcome to come in.
Often, yes. Age on its own isn't a reason to be declined, but lenders will ask how you'll repay the loan after you stop working. We help you put that plan together before you apply.
Yes. Much of Wentworth Falls is on or near bushfire-prone land and lenders finance these homes every day. You'll need building insurance from settlement, so get a quote early.
No. The lender pays us when your loan settles.
General information only. Eligibility criteria apply.
Wentworth Falls sits in the Upper Mountains, in the Blue Mountains council area. We also help buyers and owners in Bullaburra, Lawson, Leura, Katoomba and Hazelbrook, and right down the range to Glenbrook.
See our main page for a mortgage broker Blue Mountains, or all our locations.
A few local things can change a lender's view, and it pays to know before you buy or renovate:
The lender pays us when your loan settles, so there's no broker fee.
Tell us what you're planning and we'll show you what you can borrow, what it will cost and which loan suits. Free, no obligation. Call (02) 4744 2054 or fill out the form.
office@lendlocal.com.au · 39e Park St, Glenbrook NSW 2773
30 seconds. A local broker will call you back.
At the 2021 Census, 47% of Wentworth Falls households owned their home outright. If that's you, your home may be your biggest source of borrowing power. Owners come to us to fund a renovation that lets them stay put for the long run, to help a son or daughter with a deposit, or to buy an investment property. We compare a loan secured against your home across 70+ lenders and show you the repayments before you commit. Our guide to using equity to renovate walks through how lenders work out what you can access.
If you'd rather back your child's loan than hand over cash, a guarantor loan lets them buy with a smaller deposit, using part of your home as extra security. We talk the risks through with you as well as with them.
With a median age of 50 and nearly three in ten residents aged 65 or over at the 2021 Census, plenty of Wentworth Falls borrowers are taking on a loan that runs past the end of their working life. Age on its own isn't a reason to be turned down. Lenders want to know how you'll repay the loan once your pay stops: from super, from selling and downsizing, or from other assets. A lot of locals also work part-time (37% of employed residents, against 30% across NSW), and lenders treat that income differently from a full-time wage. We know which lenders are comfortable with each situation, and we set out your plan so it's assessed properly.
Houses in Wentworth Falls have mostly been valued at around $1.1m this year. That's above the $1m limit for the NSW first home buyer stamp duty concession on an existing home, so on most houses here you'll pay full stamp duty, and we build that into your budget from the first conversation. The government's 5% Deposit Scheme can still help: eligible first home buyers can buy with a 5% deposit and no lenders mortgage insurance up to the price cap for the area, and we'll check the cap for the exact property. Smaller cottages can come in under $1m, where the concession may apply. Our first home buyer home loans page covers every scheme.
A third of Wentworth Falls households (33.8%) were paying off a mortgage at the 2021 Census, with median repayments of $2,080 a month. If your loan is a few years old, there's a fair chance a new customer is being offered a better rate than you. We'll review it for free across 70+ lenders and only suggest refinancing if it saves you money after costs.
You'll talk to a real person at our Glenbrook office. Justin Leaney, our principal, is a Blue Mountains local with more than 15 years in lending, and the same person stays with your loan from the first chat to settlement. See all our home loans.