Refinancing, renovating or buying in Hazelbrook? We're a mortgage broker based in Glenbrook, about 25 minutes down the highway, and we compare 70+ lenders to find a home loan that fits a Mid Mountains family home, whether that's freeing up equity for an extension or finally getting a better rate on the loan you've had for years. The lender pays us when your loan settles, so our advice costs you nothing.
A local broker will call you within 1 business hour. No fees, no obligation.
Most Hazelbrook clients already own their home. They want a sharper rate, money to renovate or extend, or a bigger place without leaving the Mountains. We also help first home buyers getting a foot in the door.
Nearly half of Hazelbrook households have a mortgage. If you haven't checked your rate in a couple of years, we'll compare it against 70+ lenders and tell you honestly whether switching is worth it after costs.
Plenty of Hazelbrook homes are older and on good-sized blocks. We work out how much of your equity you can use for a renovation, an extension or a knock-down rebuild, and which loan suits the job.
Growing family or buying your first place? We'll show you what you can borrow, which schemes and stamp duty savings apply, and get you a pre-approval before you start going to opens.
Whatever you’re trying to buy, build or restructure — there’s a lender on our panel for it.
Penrith remains one of Sydney’s most attractive entry points. We walk you through the First Home Guarantee, stamp duty concessions and which suburbs your budget can realistically reach.
Learn more →If you haven’t checked your rate lately, you’re likely paying a “loyalty tax.” We offer a free health check across 70+ lenders and only recommend switching if the numbers stack up.
Learn more →With the new Western Sydney Airport, Metro line and Aerotropolis, Penrith’s growth story is accelerating. We structure loans for tax efficiency, future borrowing capacity and long-term growth.
Learn more →Building in Jordan Springs, Caddens or Penrith Lakes? Construction loans involve progress payments and builder valuations. We coordinate with your builder and lender so funding flows smoothly.
Learn more →We specialise in alt-doc and specialist lending. We know how to present your BAS statements, business activity and accountant declarations to get you the same competitive rates as PAYG.
Learn more →In a competitive market — especially Glenmore Park, Cranebrook and Emu Plains — pre-approval gives you the confidence to bid at auction or make a serious offer when the right property comes up.
Learn more →No jargon, no surprises. Just clear advice and a clear plan from your first call to well beyond settlement.
We’ll get to know your goals, your situation and what kind of loan you actually need. No commitment, no pressure.
We compare across 70+ lenders and come back with two or three real options, explained in plain English — rate, repayments, features and total cost.
We handle the paperwork, chase the lender, and keep you in the loop the whole way. You sign — we do the rest.
We don’t disappear once your loan settles. We review your rate annually and we’re always a phone call away if your situation changes.
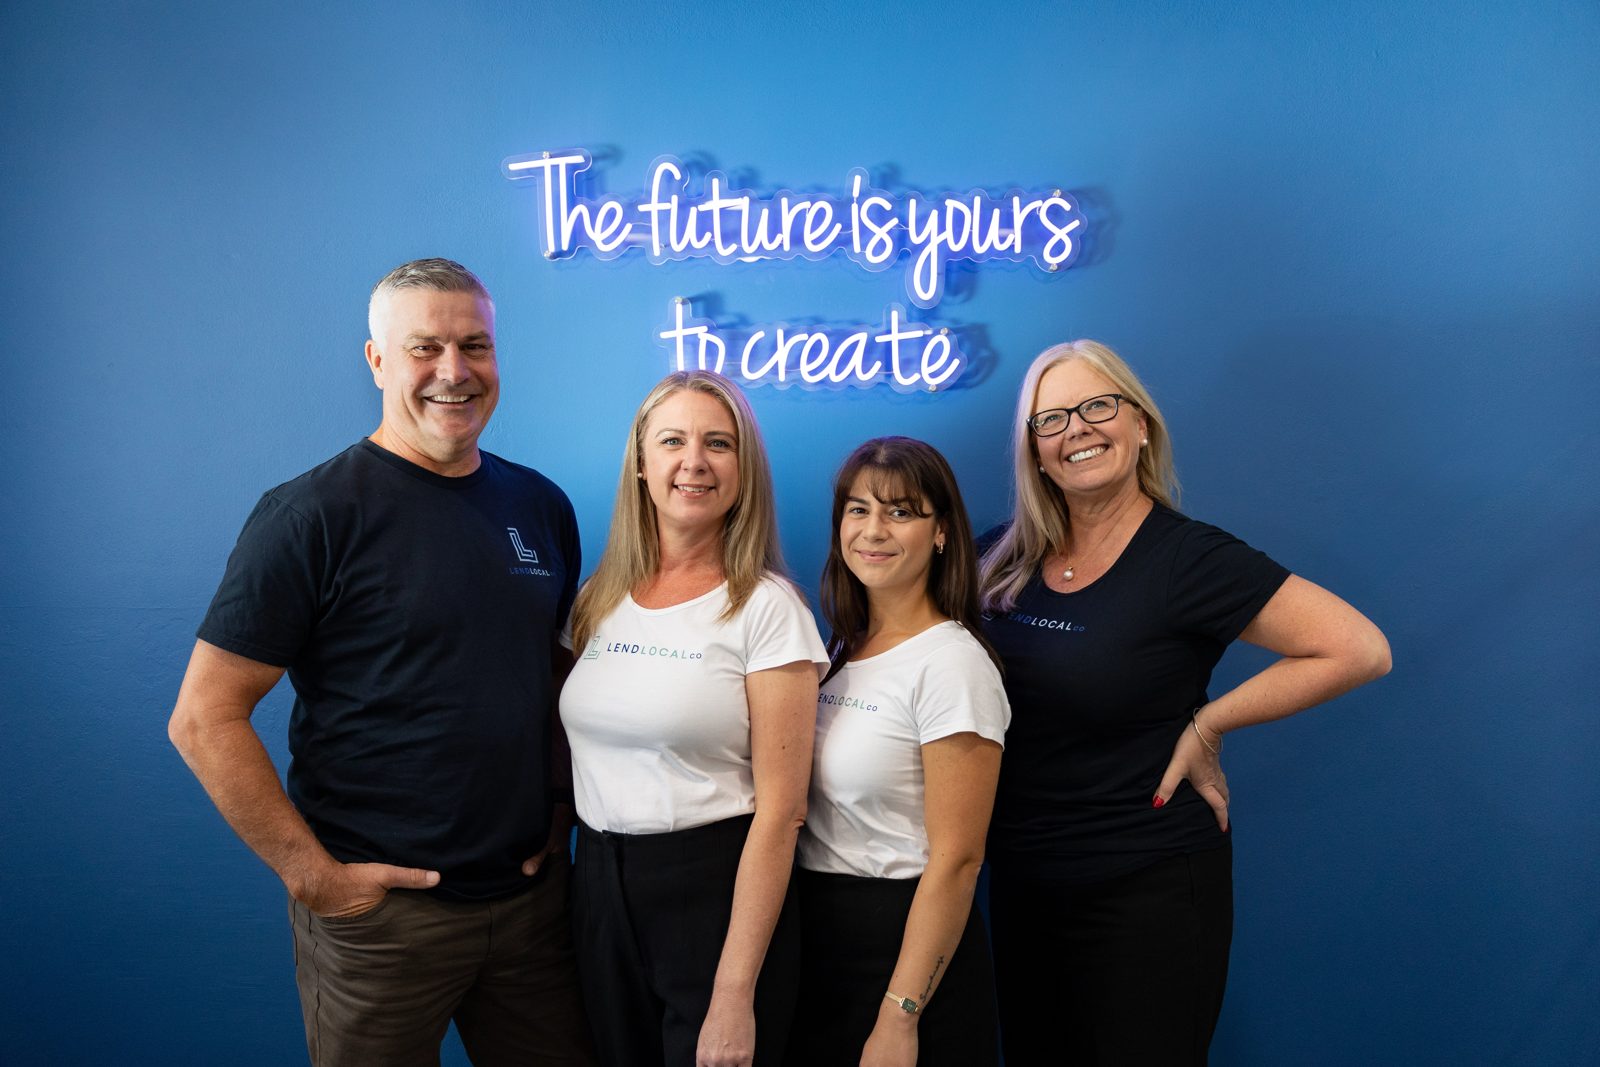
We’re not a call centre or a faceless online form. When you work with Lend Local Co, you get a small, tight-knit team of mortgage professionals who live and work in the same community you do.
From your very first call to the day your loan settles, you’ll deal with the same people — people who remember your name, understand your goals, and pick up the phone when you ring.
Free calculators and plain-English guides from our team. Use them to get a rough idea, then we'll check the real numbers across 70+ lenders.
See roughly how much a lender could let you borrow based on your income and expenses.
Estimate your weekly, fortnightly or monthly repayments at different rates and loan sizes.
See how much interest and time you could save by paying a little extra each month.
Worked examples for a unit and a house, the 5% Deposit Scheme and stamp duty.
What you can borrow, grants and schemes, and why pre-approval matters.
From a rate starting with 6 to an expiring fixed term, when a review pays off.
Full-doc, low-doc and alt-doc explained, and how to strengthen your application.
No. Our office is on Park Street in Glenbrook, about 25 minutes down the highway, and we also see clients at our Windsor office by appointment. Most Hazelbrook clients do everything by phone and video, but you're welcome to come in.
Usually, yes. If you've built up equity, we can look at a top-up on your current loan, a refinance to a lender with a better rate, or a construction loan for bigger jobs. We'll compare all three.
Yes. Much of Hazelbrook is on or near bushfire-prone land and lenders finance these homes every day. You'll need building insurance from settlement, so get a quote early.
No. The lender pays us when your loan settles.
General information only. Eligibility criteria apply.
Hazelbrook sits in the Mid Mountains, in the Blue Mountains council area. We also help buyers and owners in Lawson, Woodford, Linden, Bullaburra and Faulconbridge, and right down the range to Glenbrook.
See our main page for a mortgage broker Blue Mountains, or all our locations.
A few local things can change a lender's view, and it pays to know before you buy or renovate:
The lender pays us when your loan settles, so there's no broker fee. The same person stays with your loan from the first chat to the keys.
Tell us what you're planning and we'll show you what you can borrow, what you could save and which loan suits. Free, no obligation. Call (02) 4744 2054 or fill out the form.
office@lendlocal.com.au · 39e Park St, Glenbrook NSW 2773
30 seconds. A local broker will call you back.
At the 2021 Census, 46.8% of Hazelbrook households owned their home with a mortgage, compared with 32.5% across NSW. A lot of those loans were set up years ago, and lenders often save their sharpest rates for new customers. We'll review your loan for free, compare it with 70+ lenders, and only suggest refinancing if it actually saves you money once costs are counted. If your current loan is already a good deal, we'll tell you that too.
Hazelbrook has a lot of solid older homes, and plenty of owners would rather improve what they have than move. If you've built up equity, you may be able to borrow against it for a new kitchen, an extra bedroom or a second storey. For bigger jobs, a construction loan pays your builder in stages as the work is done, so you only pay interest on what's been drawn. We'll help you line up the quotes, the valuation and the loan in the right order.
A third of employed Hazelbrook residents worked from home at the 2021 Census, and many of them run their own business. Lenders want to see self-employed income a certain way, and the right lender can make a big difference to how much you can borrow. Our self-employed home loans page explains what to have ready.
Need more room but want to stay in the Mountains? We'll work out what you can borrow before you list, and whether a bridging loan makes sense so you're not stuck between two settlements.
Buying your first home in Hazelbrook? Houses here have mostly been valued between $800,000 and $1m, where eligible first home buyers get a NSW stamp duty concession rather than a full exemption, so you pay some duty but a lot less than the full amount. The government's 5% Deposit Scheme lets you buy with a 5% deposit and no lenders mortgage insurance up to the price cap for the area, and we'll check the cap for the exact property. We cover every scheme you're eligible for as part of our first home buyer home loans service, then get you a pre-approval so you know your budget.