Looking for a mortgage broker in Springwood? We're based in Glenbrook, about 15 minutes down the highway, and we compare 70+ lenders for Springwood buyers and owners. Springwood has everything from family homes on big blocks to villas and units a short walk from the station, and lenders treat each of them differently. Whether you're buying a unit on one income, moving into a villa after the kids have left or buying your first place, we'll find the lender that fits the property and your situation. The lender pays us when your loan settles, so our advice costs you nothing.
A local broker will call you within 1 business hour. No fees, no obligation.
What you're buying in Springwood can matter to a lender as much as what you earn. We help with villas and units, loans on one income, downsizing and first homes.
Lenders read the strata report, the building and the size of the unit. We check those early so the loan doesn't stall at the valuation.
Nearly 30% of Springwood households are one person living alone. We help single-income buyers find a lender that fits, and show you what you can borrow before you start looking.
Selling the family home and buying a villa in town? We'll sort out the timing, the deposit and whether you need a loan at all.
Whatever you’re trying to buy, build or restructure — there’s a lender on our panel for it.
Buying your first home? We'll walk you through the 5% deposit scheme, the stamp duty concessions and what your budget can realistically buy in the suburbs you're looking at.
Learn more →If you haven't checked your rate lately, you could be paying a "loyalty tax". We'll run a free health check across 70+ lenders and only recommend a switch if the numbers stack up.
Learn more →Buying an investment property, or your next one? We set up investment loans with tax, future borrowing power and long-term growth in mind, and work with your accountant on the structure.
Learn more →Building, or knocking down and rebuilding? Construction loans use progress payments and a valuation of the finished home. We work with your builder and lender so each payment is released on time.
Learn more →Self-employed, contracting or running a small business? We know how each lender looks at BAS statements, business income and accountant letters, and which ones are most likely to say yes.
Learn more →When the right place comes up, it doesn't sit on the market for long. Pre-approval means you can bid at auction or make a serious offer knowing roughly what a lender will approve.
Learn more →No jargon, no surprises. Just clear advice and a clear plan from your first call to well beyond settlement.
We’ll get to know your goals, your situation and what kind of loan you actually need. No commitment, no pressure.
We compare across 70+ lenders and come back with two or three real options, explained in plain English — rate, repayments, features and total cost.
We handle the paperwork, chase the lender, and keep you in the loop the whole way. You sign — we do the rest.
We don’t disappear once your loan settles. We review your rate annually and we’re always a phone call away if your situation changes.
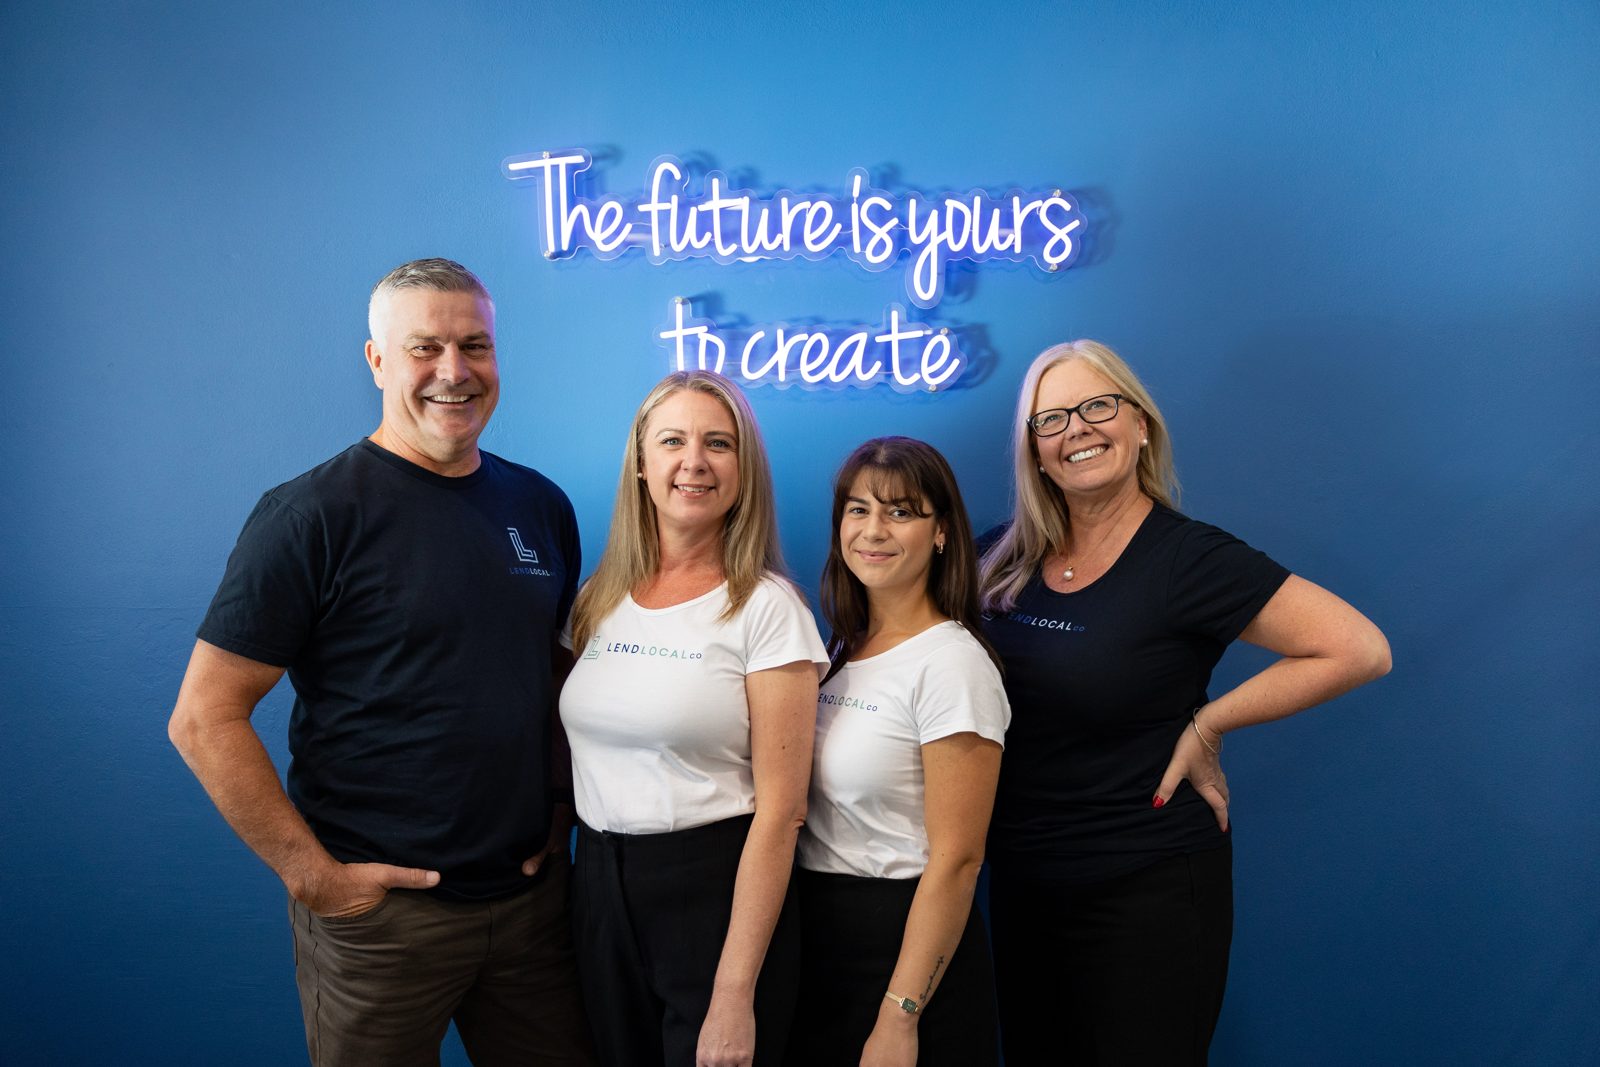
We’re not a call centre or a faceless online form. When you work with Lend Local Co, you get a small, tight-knit team of mortgage professionals who live and work in the same community you do.
From your very first call to the day your loan settles, you’ll deal with the same people — people who remember your name, understand your goals, and pick up the phone when you ring.

Free calculators and plain-English guides from our team. Use them to get a rough idea, then we'll check the real numbers across 70+ lenders.
See roughly how much a lender could let you borrow based on your income and expenses.
Estimate your weekly, fortnightly or monthly repayments at different rates and loan sizes.
See how much interest and time you could save by paying a little extra each month.
Worked examples for a unit and a house, the 5% Deposit Scheme and stamp duty.
What you can borrow, grants and schemes, and why pre-approval matters.
From a rate starting with 6 to an expiring fixed term, when a review pays off.
Full-doc, low-doc and alt-doc explained, and how to strengthen your application.
Often, yes. Lenders look at your income, your assets and how you'll repay the loan if it runs past retirement. A smaller loan with a clear plan to pay it down is easier to get approved.
No. Our office is on Park Street in Glenbrook, about 15 minutes down the highway, and walk-ins are welcome. We also see clients at our Windsor office by appointment, and plenty of people sort everything out by phone and video.
No. The lender pays us when your loan settles.
General information only. Eligibility criteria apply.
Springwood sits in the Mid Mountains, in the Blue Mountains council area. We also help buyers and owners in Winmalee, Yellow Rock, Valley Heights, Sun Valley, Faulconbridge and Hazelbrook, and down the hill in Glenbrook.
See our main page for a mortgage broker Blue Mountains, or all our locations.
A few local things can change a lender's view, and they're worth checking before you sign:
The lender pays us when your loan settles, so there's no broker fee.
Tell us what you're planning and we'll show you what you can borrow, how lenders will see the property and which lender suits. Free, no obligation. Call (02) 4744 2054 or fill out the form.
office@lendlocal.com.au · 39e Park St, Glenbrook NSW 2773
30 seconds. A local broker will call you back.
Before a lender approves a loan on a villa or unit, it wants to know the building is in good shape and the owners corporation isn't short of money. A big special levy coming up, or a building defect, can change the lender's answer or your budget.
Size matters too. Some lenders cap the loan or ask for a bigger deposit on very small units, often under about 40 to 50 square metres of living space. We'll ask for the strata report and floor plan early and match you with a lender that's comfortable with the property. Compare home loans from 70+ lenders with us in one go.
At the 2021 Census, 29.2% of Springwood households were one person living alone. Borrowing on one income is harder because lenders test your repayments at about 3 percentage points above the actual rate, and there's no second pay to absorb it. They also differ on how they count overtime, bonuses and a second job.
We'll run your numbers against several lenders and show you the difference before you apply, so you know whether a unit, a villa or a small house is in reach. If you already own and the repayments feel heavy on one wage, a refinancing review is free, and we'll only suggest a switch if it saves you money after costs.
When the family home gets too big, many Springwood owners want to stay close to the shops, the station and their doctor, which usually means a villa or townhouse in town. If you're selling a house worth around $1.1 million and buying a villa for less, you may not need a loan at all. If you do, the question is usually timing: buy first and carry two properties for a while, or sell first and rent.
We'll set out the costs of each and check which lenders will lend at your age and on your income, including super or a part pension. Lenders will ask how you'll repay a loan that runs past retirement, so we'll help you answer that up front.
Retirement village units are different. One sold on a lease or licence usually can't be bought with a standard home loan, while an over-55s villa on its own strata title often can.
Springwood units have sold for about $880,000 over the past year, which puts most of them in the NSW first home buyer stamp duty concession band (over $800,000 and under $1 million), so eligible buyers pay reduced duty. Houses have sold for around $1.1 million, so most sit above the $1 million line where the concession stops. Know that before you choose between a unit and a house.
The government's 5% Deposit Scheme can let you buy with a 5% deposit and no lenders mortgage insurance, up to the price cap for the area, and we'll check the cap for the exact property. Our first home buyer home loans service covers every scheme, the real upfront cost and a pre-approval before you bid.
You'll talk to a real person at our Glenbrook office. Justin Leaney, our principal, is a Blue Mountains local with more than 15 years in lending, and the same person stays with your loan from the first chat to settlement. Springwood has its own brokers, and a second opinion from us costs you nothing.