Buying, building or refinancing along the Hawkesbury — from Windsor and Richmond out to Pitt Town and North Richmond — is one of the biggest financial decisions you’ll make, and walking into a branch hoping for a good rate isn’t a plan. From our office on Christie Street in Windsor, we compare 70+ lenders to structure a loan around you, not the bank. And because the lender pays us, our advice costs you nothing.
A local broker will call you within 1 business hour. No fees, no obligation.
Plenty of brokers will quote you a rate over the phone. Far fewer understand how a lender treats a lifestyle block at Pitt Town differently to a townhouse in South Windsor, or why a flood or bushfire overlay can change a valuation. We do — and we know which lenders are comfortable with the Hawkesbury’s mix of established homes, new estates and rural-residential land.
South Windsor and Bligh Park are strong value entry points; McGraths Hill and North Richmond are tightly held; acreage around Pitt Town, Windsor Downs and Freemans Reach needs a lender that will lend on land. We match you to the right one.
You’ll deal with a real person who returns calls and emails the same day — not a call-centre queue. The same team has your back from first chat to settlement.
We’re paid by the lender once your loan settles, and commissions are broadly the same across our 70+ panel. We’ve no reason to push one bank over another — only to find the loan that fits your life.
Whatever you’re trying to buy, build or restructure — there’s a lender on our panel for it.
Buying your first home? We'll walk you through the 5% deposit scheme, the stamp duty concessions and what your budget can realistically buy in the suburbs you're looking at.
Learn more →If you haven't checked your rate lately, you could be paying a "loyalty tax". We'll run a free health check across 70+ lenders and only recommend a switch if the numbers stack up.
Learn more →Buying an investment property, or your next one? We set up investment loans with tax, future borrowing power and long-term growth in mind, and work with your accountant on the structure.
Learn more →Building, or knocking down and rebuilding? Construction loans use progress payments and a valuation of the finished home. We work with your builder and lender so each payment is released on time.
Learn more →Self-employed, contracting or running a small business? We know how each lender looks at BAS statements, business income and accountant letters, and which ones are most likely to say yes.
Learn more →When the right place comes up, it doesn't sit on the market for long. Pre-approval means you can bid at auction or make a serious offer knowing roughly what a lender will approve.
Learn more →No jargon, no surprises. Just clear advice and a clear plan from your first call to well beyond settlement.
We’ll get to know your goals, your situation and what kind of loan you actually need. No commitment, no pressure.
We compare across 70+ lenders and come back with two or three real options, explained in plain English — rate, repayments, features and total cost.
We handle the paperwork, chase the lender, and keep you in the loop the whole way. You sign — we do the rest.
We don’t disappear once your loan settles. We review your rate annually and we’re always a phone call away if your situation changes.
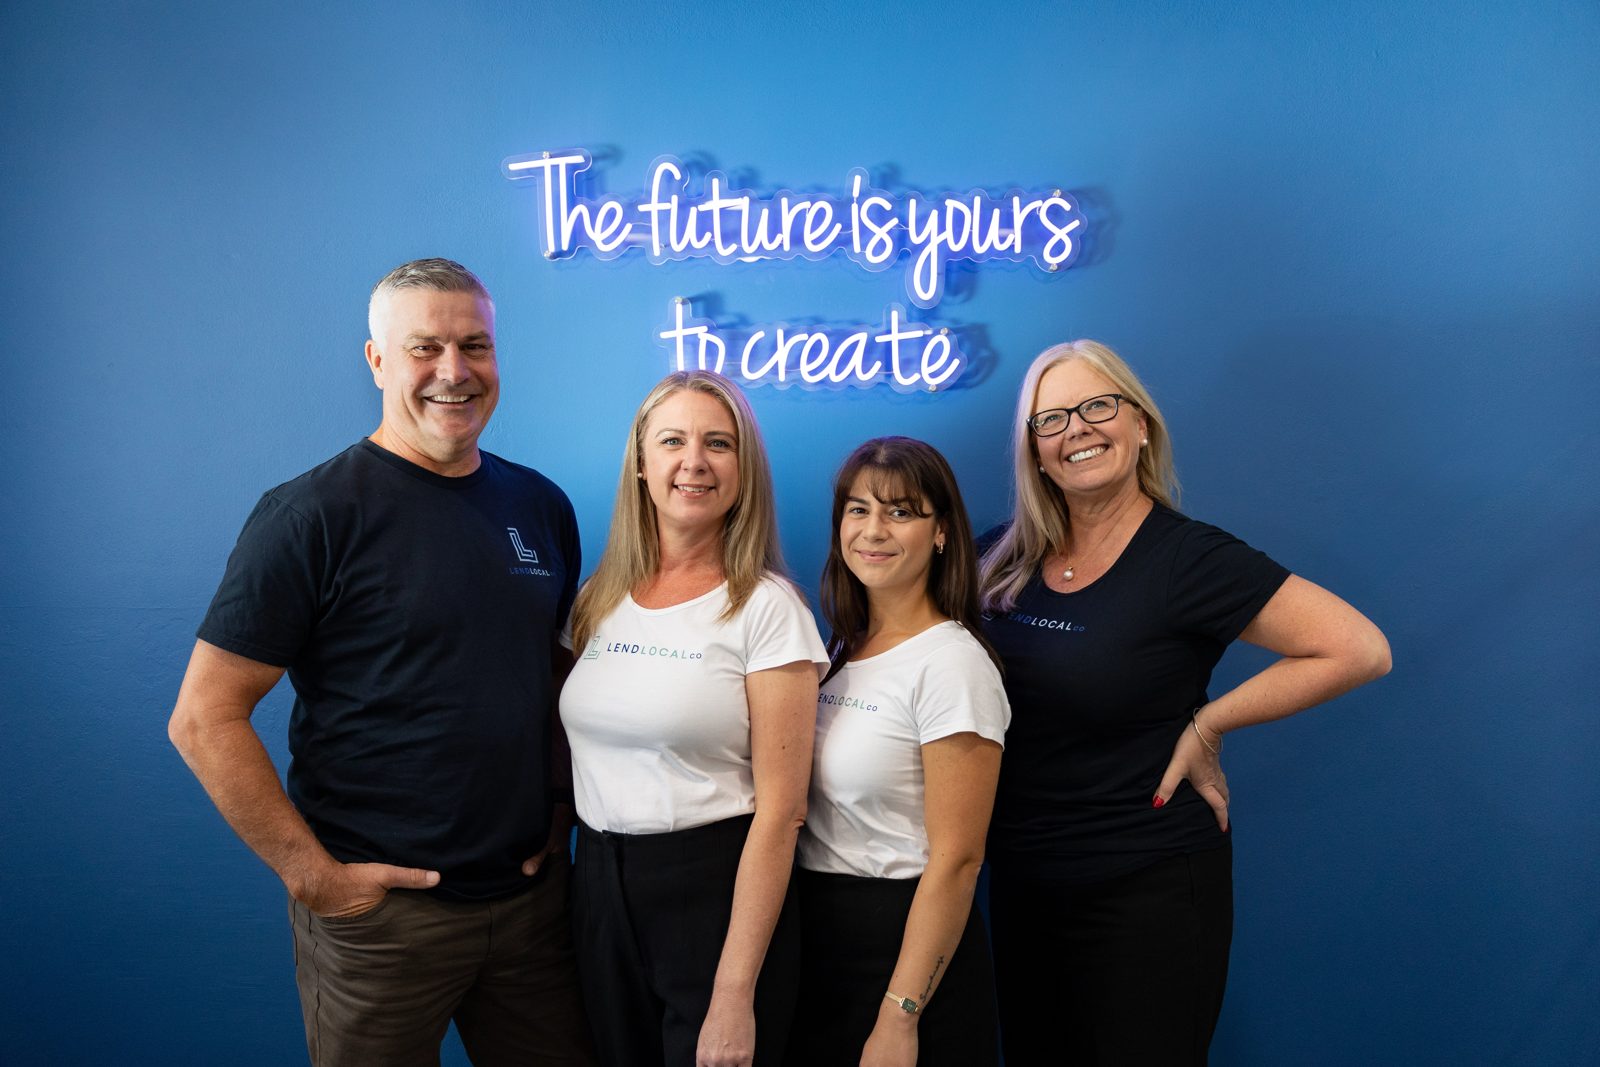
We’re not a call centre or a faceless online form. When you work with Lend Local Co, you get a small, tight-knit team of mortgage professionals who live and work in the same community you do.
From your very first call to the day your loan settles, you’ll deal with the same people — people who remember your name, understand your goals, and pick up the phone when you ring.
Pop in and say hello — our team is local to the Hawkesbury and always happy to chat through your options in person.
Free calculators and plain-English guides from our team. Use them to get a rough idea, then we'll check the real numbers across 70+ lenders.
See roughly how much a lender could let you borrow based on your income and expenses.
Estimate your weekly, fortnightly or monthly repayments at different rates and loan sizes.
See how much interest and time you could save by paying a little extra each month.
Worked examples for a unit and a house, the 5% Deposit Scheme and stamp duty.
What you can borrow, grants and schemes, and why pre-approval matters.
From a rate starting with 6 to an expiring fixed term, when a review pays off.
Full-doc, low-doc and alt-doc explained, and how to strengthen your application.
No. Lend Local Co does not charge fees to our clients. We’re paid a commission by the lender once your loan settles, and because that commission is broadly similar across our 70+ lenders, we have no financial incentive to recommend one over another.
Absolutely. From 1 October 2025 the expanded First Home Guarantee offers eligible buyers a 5% deposit with no LMI on homes up to $1.5m, with no income caps or place limits — and virtually every Hawkesbury home falls under that cap. We’ll also check the NSW First Home Buyers Assistance Scheme (no stamp duty up to $800,000, a concessional rate from $800,000 to $1,000,000) and any grants you may be eligible for.
Yes — this is a Hawkesbury speciality for us. Some lenders cap land size, treat rural zoning differently, or won’t count a second dwelling or shed. We know which lenders are comfortable with lifestyle and rural-residential blocks and how to present them.
Many Hawkesbury properties carry a flood or bushfire overlay that can affect valuation and insurance. We help you line up a lender that’s comfortable with the property and get you an insurance-ready pre-approval so it doesn’t fall over late in the process.
A straightforward pre-approval can be turned around in a few days. Full approval and settlement typically takes four to six weeks from application, depending on the lender and how quickly documents come together.
Not unless you want to. Our Hawkesbury office is at 4 Christie Street, Windsor, by appointment (call 02 4504 8875), and our Glenbrook office takes walk-ins. We’re just as happy to run everything over phone, email, video call and digital signing.
We work with clients right across the Hawkesbury local government area and surrounding districts.
Windsor, South Windsor, Richmond, North Richmond, Windsor Downs, Clarendon
Bligh Park, McGraths Hill, Pitt Town, Mulgrave, Vineyard
Freemans Reach, Wilberforce, Ebenezer, Grose Vale, Kurrajong, Glossodia, Cattai
We’re also just down the road from Penrith and the Blue Mountains, and while we’re proudly local we help clients Australia-wide via phone, video and digital applications.
Prefer to meet in person? See our Windsor office details. By appointment.
A bank can only ever offer you one product — its own. A broker compares dozens of lenders, knows each one’s credit policies, and structures your application to maximise your chance of approval at the best available rate. For Hawkesbury borrowers specifically, that matters because:
And it costs you nothing — we’re paid by the lender when your loan settles.
Book a 15-minute chat or send a quick enquiry — we’ll get back within one business hour with a clear next step. No fees, no pressure, no jargon.
office@lendlocal.com.au · 39e Park St, Glenbrook NSW 2773
30 seconds. A local broker will call you back.
The Hawkesbury remains one of NSW’s most popular first-home-buyer regions, and support has never been stronger: the expanded First Home Guarantee (5% deposit, no LMI, up to $1.5m from 1 October 2025), the First Home Buyers Assistance Scheme and the First Home Owner (New Homes) Grant. We walk first home buyers through the deposit they really need, how LMI works, and which suburbs their budget can reach.
If you haven’t reviewed your rate lately, you may be paying more than you need to. We offer a free refinance health check across 70+ lenders and only recommend a switch if it genuinely stacks up.
With the new Richmond Bridge, the Western Sydney Airport and the Aerotropolis reshaping the region, the Hawkesbury is drawing investor interest. We structure loans for tax efficiency, future borrowing capacity and cash-flow, working alongside your accountant.
Building new or knocking down and rebuilding on an established block? Construction loans involve progress payments and builder valuations. We coordinate with your builder and lender throughout so funding flows and your build stays on track.
Run a business, farm or trade? We specialise in self-employed and alt-doc lending and know exactly how each lender assesses BAS and business income — so you get the same competitive rates as a PAYG buyer.
Buying a lifestyle block or rural-residential property comes with its own lending rules — land-size caps, zoning, sheds and second dwellings. We match you with lenders comfortable with acreage and structure the application to give it the best possible run.